These are two cities that almost everyone has an opinion about before they’ve looked at a single listing. It helps to weigh the pros and cons of living in Manhattan early on. And once you actually start comparing the numbers, the differences are sharper than most buyers expect – extending beyond price to how the whole buying process works, what you’re legally purchasing, and what you’ll owe every year after closing.
Understanding how New York County stacks up against Cook County isn’t just useful background. It’s what lets you set a realistic budget and timeline before you waste a weekend flying out to look at the wrong kind of property.
Comparing the Manhattan and Chicago Real Estate Markets
Manhattan currently has around 5,715 homes available, which gives buyers a real pool of inventory to work with. Those homes are sitting on the market for roughly 84 days before selling – long enough that you’re not forced to decide in 48 hours, but don’t mistake that for a soft market.
Chicago operates on a different scale. The city spreads across a much larger landmass than Manhattan, an island where high-rise living isn’t a lifestyle choice so much as a geographic reality. That geography shapes everything – from how buildings are structured to how ownership is actually defined on paper.
If you’re relocating between these two cities, prepare for the transaction itself to feel different. A Manhattan purchase almost always involves board approvals and financial disclosures that would stop a Chicago buyer cold the first time they encountered them. Chicago deals – whether a condo or a single-family home – follow a far more conventional process.
Cost of Living and Home Prices
Manhattan’s median sale price sits at approximately $1,450,000 as of mid-2026. Buyers are paying close to full ask, with the average sale-to-list ratio running around 99.3%. There’s not much room to negotiate your way into a deal here.
Chicago tells a different story. Recent 2026 data puts the median home sale price somewhere between roughly $410,000 and $427,000. Put plainly: a budget that buys you a one-bedroom apartment in Manhattan could buy a multi-bedroom home or a luxury downtown condo in Illinois.
Average Home Prices
Manhattan’s $1.45 million median reflects a market built on premium high-rises and historic properties. Even with 8.2 months of supply currently available, the entry point is steep and that’s not changing.
Chicago buyers have more room to maneuver. That $410,000 to $427,000 median opens up real choices – in neighborhoods, building amenities, and square footage – that simply don’t exist at comparable price points in New York.
Property Taxes in New York County vs Cook County
New York County’s tax structure is genuinely confusing the first time you see it. The city’s nominal 2026 tax rate applied to assessed value is 19.843%, but assessed value is only a fraction of market value – so the effective rate for condos and co-ops lands somewhere between roughly 1.3% and 1.45%, depending on the source.
Cook County calculates things differently, and the result is a higher effective rate. Most sources put it at around 1.9% to 2.1% of market value. These annual carrying costs matter, and they belong in your long-term budget from day one.
Housing Types and Architecture
Co-ops make up roughly 70% to 85% of Manhattan’s housing stock. Condominiums account for about 20% to 25%, and brownstones or townhouses make up the small remainder.
That breakdown matters more than most out-of-town buyers realize. When you purchase a co-op, you’re not buying real property – you’re buying shares in a corporation. That distinction drives specific financial requirements and board approvals that have no equivalent in a standard real estate transaction anywhere else in the country.
What to Expect in Manhattan
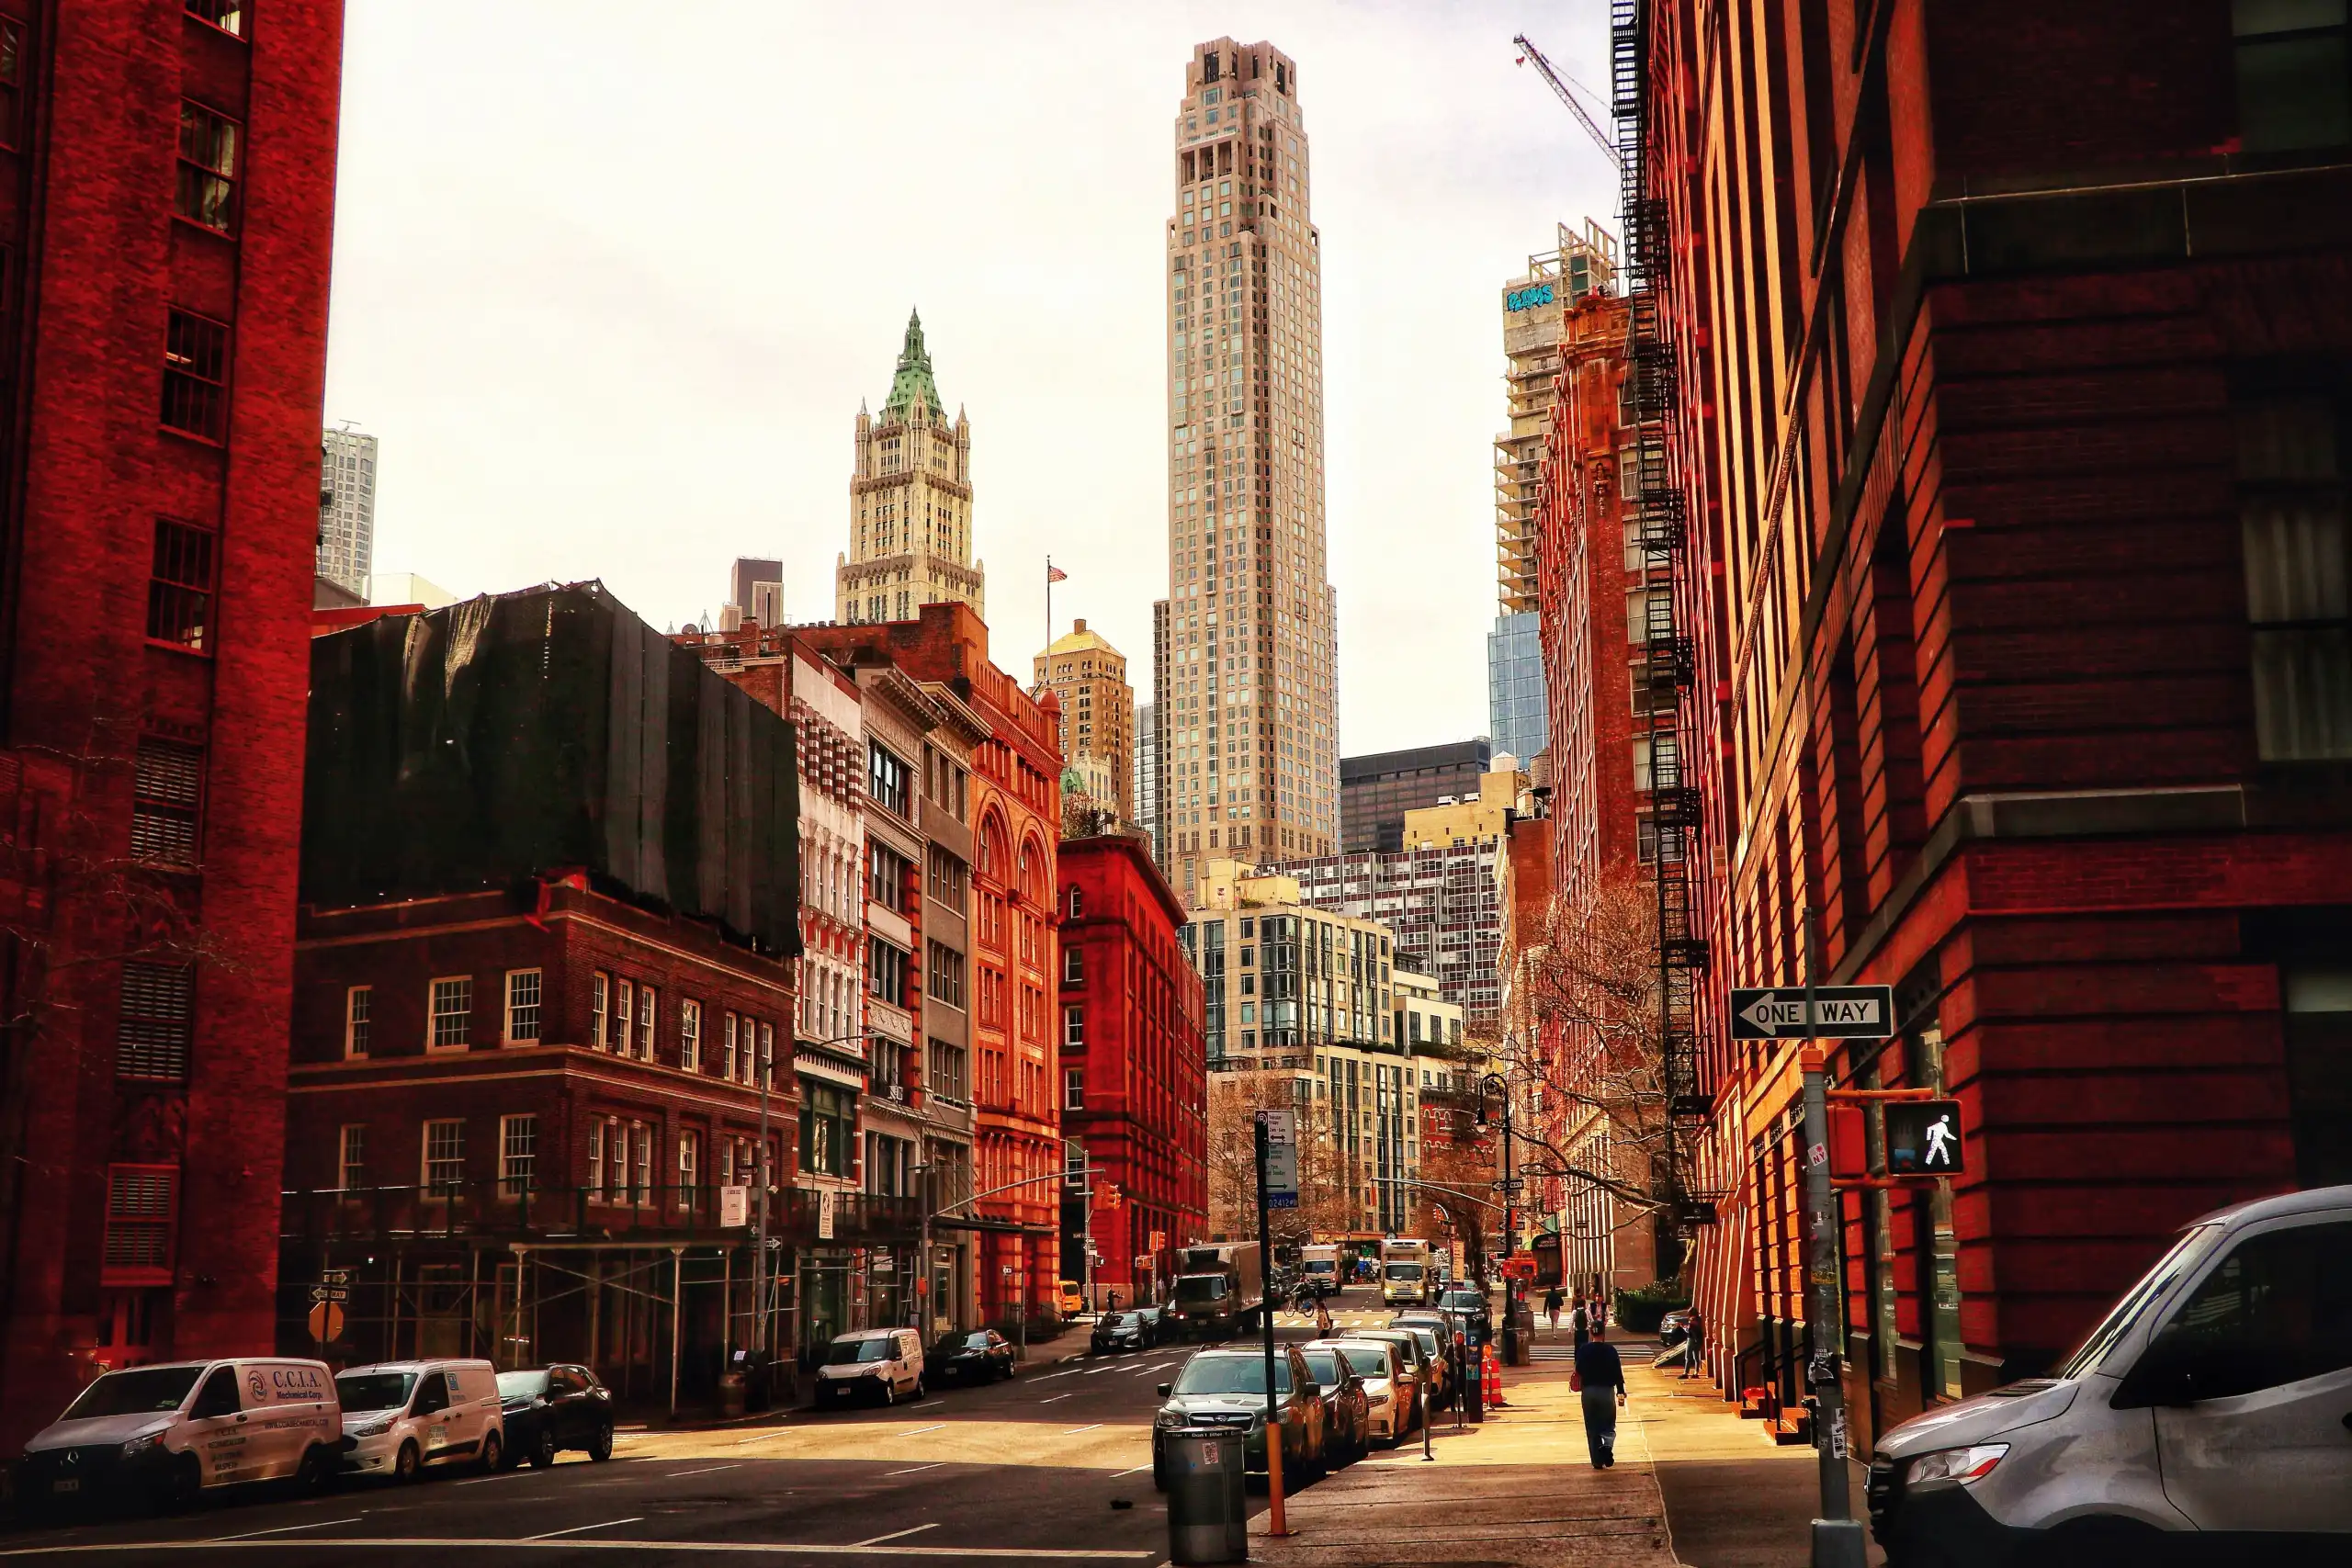
Most of the co-op and condo inventory lives in high-rise buildings, particularly in Midtown and along the major avenues. Historic brownstones and townhouses are concentrated in specific neighborhoods – the West Village, Chelsea, the Upper West and East Sides – and they carry their own set of quirks and costs.
If you’re looking at co-ops, get ready for serious financial scrutiny. Building boards routinely require buyers to demonstrate high post-closing liquidity and low debt-to-income ratios. It’s not a formality. Boards reject buyers, and they don’t have to explain why.
How it Compares to Chicago Real Estate
Chicago’s housing stock runs to traditional condominiums, multi-unit buildings, and single-family homes. Co-ops exist there – particularly along the lakefront – but they’re a small fraction of the market. The board approval process that defines Manhattan purchasing is rare in Illinois.
Condo associations in Chicago are largely focused on whether you can get a mortgage and pay your monthly HOA dues. The marathon financial review that Manhattan co-op boards put buyers through is simply not the norm.
Transit and Relocation Logistics
The straight-line driving distance between Manhattan, NY and Chicago, IL runs approximately 710 to 790 miles depending on the route. Daily commuting between them isn’t a real option, so buyers splitting time between the two cities are looking at air travel and strong local transit in each market.
In both cities, proximity to a train line is a primary driver of real estate value. That’s one of the few things these two markets genuinely have in common.
Local Public Transit: MTA vs CTA
Manhattan runs on the MTA subway – 24 hours a day, connecting the borough to Brooklyn, Queens, and the Bronx. Most residents live within a few blocks of a station. Personal vehicles are more of a liability than an asset here.
Chicago runs on the CTA train network and the Metra commuter rail system. The CTA covers the city’s core and outer neighborhoods well, but car ownership is more common in Chicago than in Manhattan, particularly for residents who live further from the downtown Loop.
Traveling Between the Cities
Direct flights from New York area airports – JFK, LGA, or EWR – to Chicago’s O’Hare (ORD) or Midway (MDW) take roughly 2.5 to 3 hours. For anyone who travels between the two regularly, that flight time is a real variable in the home search.
It’s worth knowing your airport access when you’re choosing a neighborhood. Something like the CTA Blue Line to O’Hare can take meaningful time off a regular travel schedule.
Making the Move Between Markets
With Manhattan homes spending a median of 84 days on the market in 2026, you have time to be deliberate. You’re not going to lose every apartment you look at before you can schedule a second showing.
Connect with a local agent early – ideally someone who understands both how co-op board packages work and how a standard condo purchase moves. The timeline for a cross-country relocation is longer than most buyers plan for, and a board rejection late in the process can derail everything. Comparing transit access, neighborhood options, and monthly carrying costs in each city is what turns a general interest in moving into a decision you can actually execute.
Frequently Asked Questions
How much square footage can I expect for a $1 million budget in Manhattan compared to Chicago, IL?
You’ll get considerably less in Manhattan. With the median home price around $1,450,000, a $1 million budget typically buys a one-bedroom or smaller apartment. In Chicago, where the median runs roughly $410,000 to $427,000, that same budget can put you in a large condo or a multi-bedroom home.
How do Manhattan’s monthly co-op maintenance fees compare to standard condo HOA dues in Chicago?
It depends on the building and property type. Co-ops make up 70% to 85% of Manhattan’s market and carry specific financial requirements set by each building’s board. The best approach is to pull the exact monthly carrying costs for any specific property you’re considering – in either city – and see what’s actually included.
Will I have to pass a board interview to buy an apartment in Manhattan, NY if I am relocating from Chicago?
Yes, if you’re buying a co-op. Co-ops dominate Manhattan’s housing stock, and boards require extensive financial disclosures and a formal interview before they’ll approve a sale. Condominiums in Manhattan don’t typically require that process.
Which real estate market has historically offered better long-term property appreciation: Manhattan or Chicago?
It depends on the specific neighborhood and property type. Manhattan currently commands a median of $1,450,000 while Chicago’s median ranges from $410,000 to $427,000. A local agent can walk you through recent sales data for specific buildings if you want to evaluate long-term trends properly.
Are property taxes and closing costs higher for buyers in Manhattan, NY than in Chicago?
It depends on how you measure it. Cook County’s effective property tax rate runs around 1.9% to 2.1% of market value, which is higher than New York County’s effective rate of roughly 1.3% to 1.45% for condos and co-ops. That said, Manhattan’s higher purchase prices tend to produce larger upfront closing costs overall.
Do Manhattan luxury buildings offer the same level of in-unit amenities, like washer/dryers, as newer high-rises in downtown Chicago?
It depends on the building’s age and property type. Manhattan’s stock is dominated by co-ops and historic brownstones, which can differ significantly in amenities from newer construction. Verify specific in-unit features with your agent when you’re touring – don’t assume anything is standard.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).