The Franco Report | Quarterly, Curated, Confidential
Manhattan, distilled. Quarterly insight from Michael J. Franco, the market, the city, and everything worth knowing before it becomes common knowledge.
Better than you might guess, considering higher mortgage rates, economic uncertainty, and concerns surrounding New York’s new pied-a-terre tax. The Manhattan residential real estate market demonstrated considerable strength during the third quarter of 2026. In fact, the quarter produced some of the strongest results we have seen in several years. Sales increased, prices continued to rise, apartments sold more quickly, and inventory remained constrained.
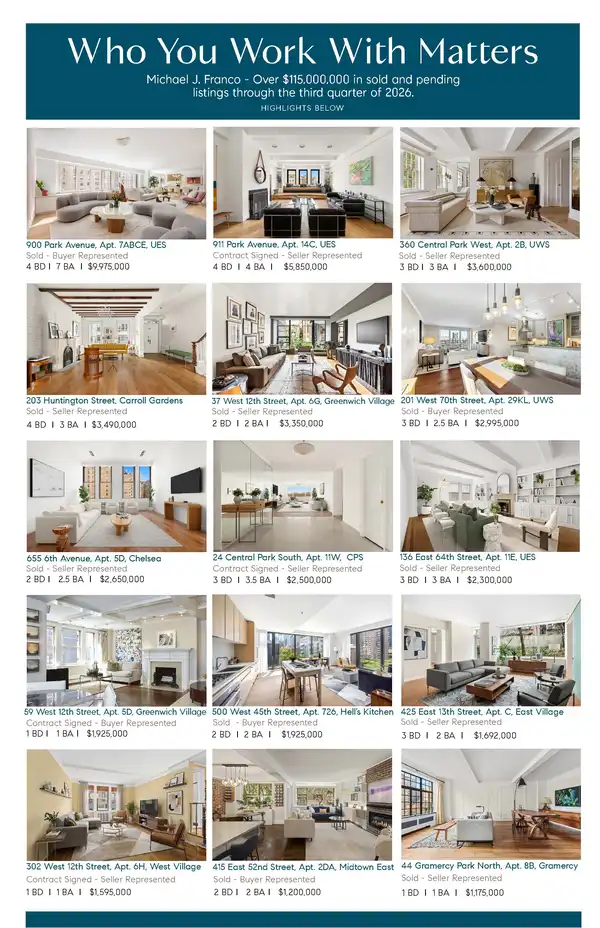
Michael J. Franco, over $115,000,000 in sold and pending listings through the third quarter of 2026.
Manhattan Sales Volume Climbed 9% in Q3 2026
Sales volume was up 9% over the same period last year, with 3,625 apartment closings during the third quarter. This also represents the strongest third quarter performance since 2022.
Sales increased across most price categories, but the higher end of the market was particularly strong. Sales above $3 million increased 25% compared with the same quarter last year, while sales below $3 million increased a more modest 6%. The $3 million to $5 million segment was especially active, with closings increasing an impressive 40%.
This indicates that despite the current interest rate environment, there continues to be considerable demand for larger and more expensive Manhattan apartments, particularly among buyers who are less sensitive to mortgage rates. Cash buyers remain the majority above the $3 million price point.
What Was the Median Manhattan Apartment Price in Q3 2026?
The median Manhattan apartment sales price increased 4% year over year to $1,250,000, the highest third quarter median price on record. The average sales price increased approximately 1% to $2.01 million, while the average price per square foot rose 2% to $1,751. This marked the seventh consecutive quarter with market wide price increases on a year over year basis.
These are market wide figures. Resale condominium median prices increased 10% to $1.65 million, while resale co-op median prices remained essentially unchanged at $875,000. This is another reminder that Manhattan is not one uniform real estate market. Apartment size, building type, condition, location, and price point can produce dramatically different results.
Is Manhattan Apartment Inventory Still Tight?
The ongoing inventory shortage remains. Simply put, there are not enough apartments available for sale in many of the most desirable segments of the Manhattan market. Available inventory declined 3% compared with last year to 6,354 apartments. The shortage was particularly pronounced in the $2 million to $5 million price range, where available listings declined 14%.
Resale co-op inventory fell 6%, while new development inventory declined a remarkable 22%, reaching its lowest level in nearly 14 years. Resale condo inventory, by contrast, increased 5%.
Limited inventory can create a meaningful advantage for sellers whose apartments are desirable, properly prepared, and realistically priced. It also means buyers searching for something very specific may have fewer choices than they would like.
How Fast Are Manhattan Apartments Selling in 2026?
Properties are also selling more quickly. The average marketing period declined 13% from last year to just 90 days, the shortest average in four years. This marked the ninth consecutive quarter in which the average time it took to sell an apartment declined.
These are averages. An overpriced apartment can still languish on the market for months, while a well priced and beautifully presented apartment can attract multiple offers almost immediately. Strategic pricing and proper preparation remain two of the most important factors determining the success of a sale, regardless of market conditions.
A Note of Caution: Signed Contracts Declined
To introduce a little caution amid these otherwise encouraging statistics, the number of contracts signed during the quarter declined 6% compared with last year, to 2,532 contracts. This is significant because closed sales largely reflect decisions buyers made months earlier, while signed contracts provide a more current indication of market activity and what is to come.
Part of the decline may simply reflect the shortage of available inventory. Buyers cannot purchase apartments that are not for sale, and the lack of inventory can wear buyers down to the point where they stop looking. Higher mortgage rates, economic uncertainty, and the new pied-a-terre tax may also have caused some purchasers to hesitate. Still, the decline in contracts bears watching as we move through the final quarter of the year.
What This Means for Manhattan Buyers and Sellers
We are entering the final months of 2026 with a fundamentally healthy Manhattan real estate market, but one that remains highly selective.
For sellers, limited competing inventory presents an opportunity, particularly for apartments in excellent condition and desirable locations. That does not mean buyers are willing to pay any price. Proper pricing, presentation, and marketing remain essential.
For buyers, opportunities certainly exist, especially with properties that have been on the market for an extended period or require renovation. Buyers waiting for a significant market correction should recognize that inventory remains tight and prices have continued to demonstrate resilience.
The third quarter reinforces something I have believed for many years: Manhattan real estate does not always behave the way conventional wisdom suggests it should, and it certainly does not move in lockstep with other real estate markets across the country. Despite the challenges in the market, buyers continue to purchase apartments, sellers continue to achieve strong prices, and well positioned properties continue to attract meaningful interest and sometimes multiple offers.
The key, as always, is understanding not just what the overall market is doing, but what is happening in your particular segment of the market. If you are considering a move before the end of the year, I would welcome the opportunity to discuss what these trends mean for your particular circumstances.
Before You Price a Listing: Watch the Framework
Frequently Asked Questions About the Q3 2026 Manhattan Real Estate Market
1. Why is the Manhattan real estate market performing strongly despite high mortgage rates?
Manhattan’s housing market is heavily insulated by cash buyers, particularly at the upper end. In Q3 2026, sales above $3 million increased by 25%, with the $3 million to $5 million segment surging 40%. Because a vast majority of luxury buyers in New York purchase with cash rather than traditional financing, elevated mortgage rates have had a minimal cooling effect on prime residential transactions.
2. Why did closed sales rise while signed contracts declined in Q3 2026?
Closed sales reflect contracts negotiated during late spring and early summer, capturing historical market momentum. The 6% dip in signed contracts during Q3 represents a forward-looking indicator driven primarily by persistent inventory shortages—buyers simply cannot sign contracts on properties that do not exist. Additionally, high interest rates and the recent introduction of NYC’s new pied-à-terre tax led some purchasers to take a more deliberate, cautious stance before committing.
3. What is the current median price difference between a Manhattan co-op and a condo?
In Q3 2026, resale condominiums achieved a record median price of $1.65 million (up 10% year-over-year), whereas resale co-ops held flat at a median price of $875,000. This ~47% price differential highlights that co-ops continue to offer exceptional spatial value for long-term primary buyers compared to investor-flexible condos.
4. Is it currently a buyer’s market or a seller’s market in Manhattan?
It is a highly selective seller’s market for well-priced, turn-key properties due to constrained inventory—available listings dropped 3% overall and 14% in the $2M–$5M range. Properties marketed correctly are selling in an average of 90 days (a 4-year low). However, buyers still maintain leverage on overpriced listings or homes requiring major renovations, as purchasers remain disciplined against overpaying.
5. How is new development inventory impacting choice for Manhattan luxury buyers?
New development (sponsor) inventory reached its lowest point in nearly 14 years during Q3 2026, plunging 22% year-over-year. High construction costs, financing rates, and zoning limitations have slowed new pipeline deliveries. As a result, luxury buyers seeking modern new development finishes face an exceptionally tight supply, driving increased competition for quality resale condos.
Michael J. Franco is a top producing broker at Compass, ranked #13 in Manhattan and #100 nationally by The Wall Street Journal and Real Trends. With over 20 years of experience as a broker, attorney, and investor, Michael brings legal and financial precision to every Manhattan real estate transaction. The Franco Report is his quarterly market analysis, delivered every quarter to clients, colleagues, and readers who want to understand Manhattan real estate before it becomes common knowledge.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).